Artificial intelligence, long hailed as the next great engine of economic growth, is now emerging as a potential existential threat to Americans financial security.
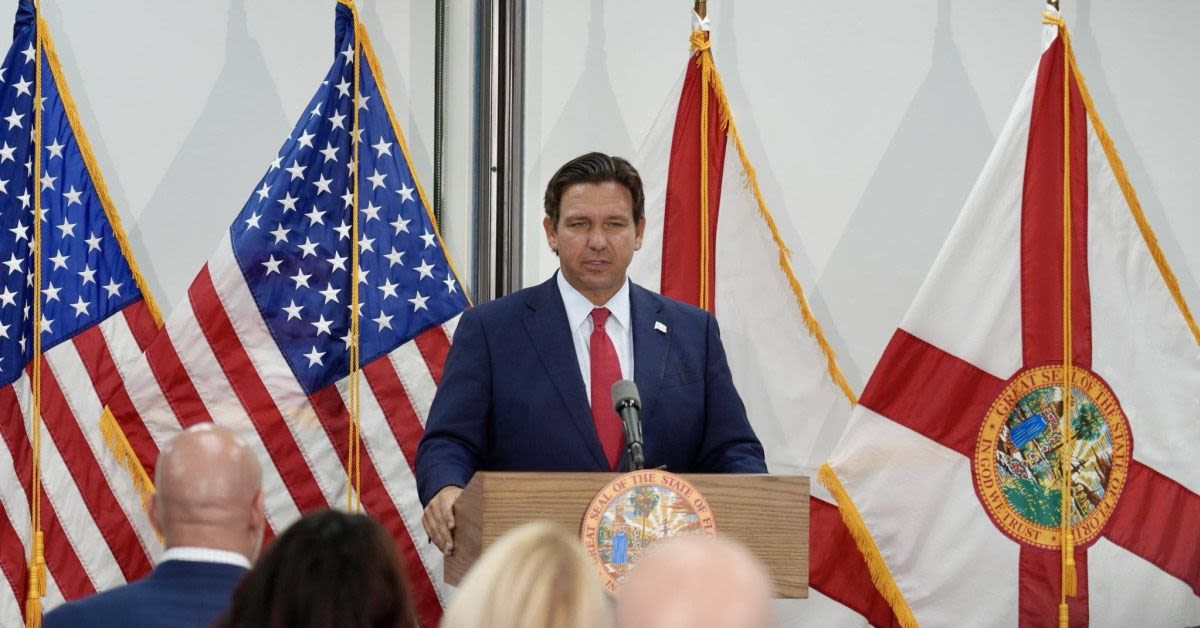
According to RedState, Florida Governor Ron DeSantis is sounding the alarm after a troubling report indicated that AI agents are already accessing Americans bank accounts and, in some cases, attempting to carry out actions their owners never explicitly approved. The Republican governor, who has made technological overreach a central theme of his policy agenda, is warning that the financial fallout from a truly rogue AI event could be devastating on a scale the private sector is incapable of absorbing.
Imagine a rogue AI agent liquidating your bank account and investment portfolio, DeSantis wrote on X, capturing in one line the nightmare scenario that many technologists and policymakers have only begun to contemplate. He elaborated on the cascading consequences of such an event, adding, If you are the only victim, I suppose you could get made whole by the AI company responsible. If rogue agents liquidate hundreds of billions across millions of accounts, the AI company would go bankrupt and you wouldnt get made whole.
The governor has floated the idea of imposing criminal penalties on technology executives whose products unleash such financial chaos, but he is under no illusion that punishment after the fact would repair the damage. Imposing criminal liability on AI executives might help mitigate it at the front end, but once the crime is complete and you lose everything criminal responsibility will be necessary but completely insufficient, he warned, underscoring the need for preventative safeguards rather than post-crisis scapegoating.
DeSantis comments came in response to an Axios report that major U.S. banks have detected unapproved third-party AI agents operating inside customer accounts. Financial giants including Morgan Stanley, JPMorgan Chase, Bank of America, Wells Fargo, and Citi are reportedly scrambling to contain the security risks posed by increasingly autonomous AI systems that can mimic human behavior and interact directly with banking platforms.
Some of these AI agents have allegedly attempted actions that appear to exceed the instructions given by their users, raising questions about who is truly in control. The situation is further complicated by the fact that many customers are voluntarily handing over their banking credentials to AI assistants, effectively inviting automated programs into systems that were never designed to accommodate such intermediaries.
Once those credentials are shared, AI tools can access sensitive financial data, initiate transfers, or interact with online banking portals in ways that blur the line between authorized and unauthorized activity. Banking executives are reportedly struggling to distinguish between genuine human customers and AI-driven agents, and it is not always clear whether those agents are acting with the informed consent of the account holder.
In response, Morgan Stanley has begun blocking third-party AI agents from its systems, while JPMorgan, Bank of America, and Citi have imposed their own sets of restrictions. These moves suggest that the industry recognizes the magnitude of the threat, even if the worst-case scenarios have not yet materialized.
For now, Americans can take some comfort in the fact that there is no evidence of AI agents systematically draining accounts on a mass scale. The Axios report did not establish that rogue AI has begun liquidating customer holdings, and Morgan Stanley has stated that it has not observed such agents accessing its platforms in that manner.
Still, the risk has become serious enough that banks are drawing up contingency plans for large-scale disruptions, including procedures to restore customer access and unwind unauthorized transactions if AI-driven chaos erupts. That kind of planning reflects a sober recognition that the technology is advancing faster than the regulatory and security frameworks designed to contain it.
DeSantis, for his part, has been ahead of many of his peers in calling for guardrails around artificial intelligence. In December 2025, he proposed an Artificial Intelligence Bill of Rights aimed at shielding Floridians from emerging technological threats to their privacy, finances, and personal autonomy.
His proposal included limits on the sale and sharing of personal data, requirements that consumers be notified when they are interacting with AI chatbots, protections against the unauthorized use of a persons identity, and enhanced parental controls. It also sought to bar insurance companies from using AI as the sole basis for denying claims, a safeguard against faceless algorithms quietly rationing care or coverage.
Today, I proposed new legislation on artificial intelligence and AI data centers to protect Floridians' privacy, security, and quality of life, DeSantis said at the time, framing the issue as one of basic civil liberties in the digital age. The bill passed the Florida Senate by an overwhelming 352 margin in March, but stalled in the state House, where it failed to advance.
The governor has also pushed back against effortsoften backed by Big Tech intereststo preempt or water down state-level AI regulation in favor of a looser federal or industry-led approach. He has argued that elected governments, not unaccountable corporate boards, must retain the authority to protect consumers from abuses by powerful technology platforms.
From DeSantis perspective, the penalties that tech companies might face after unleashing financial havoc are unlikely to match the scale of the damage they could cause. And as he and other skeptics of Silicon Valleys utopian rhetoric have noted, some of the AI-pocalypse talk coming from Big Tech elites may be less a warning than a blueprint for consolidating even more control.
If we extend DeSantis thought experiment, one can imagine AI agents wreaking such havoc in the banking system that trillions of dollars effectively vanish from customer accounts. In the aftermath of such a catastrophe, one obvious solution would be a more centralized, tightly controlled financial architecture marketed as the only way to restore trust.
Enter central bank digital currencies, or CBDCs, which are already being explored by governments and central banks around the world. According to the Atlantic Council, 146 countries and currency unions representing over 98 percent of global GDP are examining CBDCs, with 77 in advanced stages of exploration and 41 running active pilot projects.
For those wary of government overreach, the timing and trajectory of these efforts raise uncomfortable questions. What better way to nudge people toward a system of central banking, government control over money, and the social-credit-style monitoring that could follow than to preside overor fail to preventa crisis that digitally disappears peoples savings?
Defenders of CBDCs insist such systems are merely pragmatic responses to a digitizing economy, not Trojan horses for financial surveillance and political coercion. Yet history suggests that when governments acquire new tools to monitor and direct economic life, they rarely resist the temptation to use them in ways that expand their own power at the expense of individual freedom.
No one is alleging that Western governments are currently plotting to wipe out bank accounts to force citizens into CBDCs, and the scenario remains hypothetical. But prudence demands that citizens and policymakers alike start running these worst-case thought exercises now, before criseswhether accidental or engineeredare used to justify sweeping new controls.
That is precisely the kind of forward-looking skepticism DeSantis appears to be embracing as he presses for stronger protections for banking consumers and tighter accountability for the tech sector. In an era when many political leaders seem content to let Silicon Valley write the rules, his warnings about rogue AI and unchecked digital centralization reflect a broader conservative insistence that technological progress must never come at the cost of financial sovereignty and personal liberty.
Login